Car Loan Finance Online Bike Loan Repayment Calculator
Calculate motorcycle loan repayments in seconds with our Bike Loan Calculator. Compare finance options and plan your ride with confidence.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Bike Loan Details:
Important!
Bike Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Bike Loan Amortisation Calculator
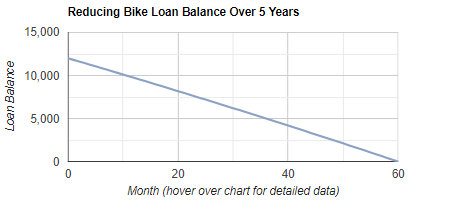
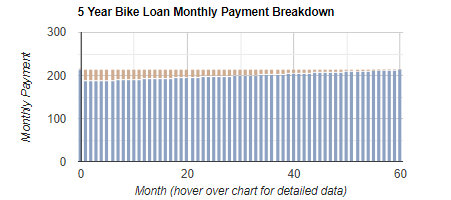
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Bike Loan Repayment Calculator
Our Bike Loan Repayment Calculator is designed to estimate your motorcycle loan repayments in seconds, so you can compare bike finance options and plan your budget before you commit. It is important because small changes to loan size, term length and interest rate can materially change your monthly repayment and the total interest you pay over the life of the loan.
This calculator provides estimates only and is not personal financial advice. Results do not take into account your objectives, financial situation or needs. Interest rates and fees vary by lender and your individual circumstances, and your final rate can only be confirmed after an application is assessed.
How to complete the form for the best result:
1. Purchase Price
Enter the bike purchase price as a whole number (no dots or commas). If you expect to borrow extra for on-road costs such as stamp duty, registration or insurance, include those amounts in the figure you enter so the estimate better reflects your likely loan amount.
2. Deposit or Trade-in Value (if applicable)
Enter your deposit or trade-in value as a whole number. If you have no deposit, enter 0. A higher deposit generally reduces the amount borrowed and can reduce interest paid over time.
3. Term of Loan (Years)
Select a term between 1 and 7 years. Longer terms typically reduce monthly repayments but can increase the overall cost of the loan due to more interest over time. Choose a term that fits your cash flow, not just the lowest repayment.
4. Interest Rate (% per annum)
Select an interest rate for the simulation. If you are unsure, test a conservative higher rate to see whether repayments remain affordable.
5. Calculate
Click calculate to generate your estimated repayment and amortisation visuals.
How to interpret the results:
1. Repayment estimate
Use the repayment figure as a starting point for budgeting, then stress-test by increasing the rate or reducing your deposit to see how sensitive repayments are.
2. Amortisation graphs
Review the loan balance chart to understand how quickly you reduce what you owe, and the interest versus principal chart to see how much of each repayment goes to interest compared with reducing the loan balance over time.
Personal car loans can help Australians finance a new or used vehicle, but the right structure depends on the borrower, the car, the lender and the total cost of borrowing. This guide explains secured and unsecured car loans, repayments, deposits, loan terms, fees, eligibility and key questions to ask before applying. - read more
The total cost of a car loan is shaped by more than the advertised interest rate. Learn how rates, fees, loan terms, deposits, balloon payments and repayment frequency can affect what you pay over time. - read more
Applying for a car loan in Australia usually involves checking affordability, preparing documents, submitting an application, lender assessment, conditional approval, vehicle checks, contract signing and settlement. This guide explains the typical steps and what can affect the outcome. - read more
Refinancing your car loan can be a game changer for your financial health. But what exactly does it mean? In simple terms, refinancing involves replacing your current car loan with a new one, usually to secure better interest rates or more favorable terms. - read more
Recent ABC Rural reporting from north-west Victoria has highlighted a fast-moving locust control problem, with farmers in the Mallee concerned about hatchings ahead of harvest and Agriculture Victoria saying numbers are at their highest level in 15 years, though not expected to reach plague levels. For machinery planning, the story is a reminder that pest pressure can quickly shift from an agronomy issue to a capital and cash-flow decision. - read more
New biodiversity offset agreements in Central West NSW are putting a fresh financial question in front of some landholders: how should long-term conservation income be weighed against restrictions on future land use? Recent ABC Rural reporting detailed NSW Government agreements covering more than 15,000 hectares to offset land affected by transmission infrastructure in the Central-West Orana Renewable Energy Zone, with the model expected to extend to other renewable energy projects. - read more
Australia’s latest inflation figures have added a fresh layer of uncertainty for car buyers, with the September 2026 Consumer Price Index showing annual inflation at 4.3 per cent and trimmed mean inflation at 3.6 per cent. Coming after the Reserve Bank of Australia lifted the cash rate target to 4. - read more
South Australian boat buyers and existing owners have a timely cost reminder as the state’s temporary registration relief moves towards its final weeks. The 50 per cent discount on recreational boat and light boat trailer registration applies to eligible registrations between 1 December 2025 and 1 December 2026, making it relevant for renewals, first-time registrations and ownership transfers completed within that window. - read more