
Car Loan Finance Online :: News
SHARE

Share this news item!

Boating Safety Reminders Put Real Ownership Costs in View

Why compliance, gear and preparation should be part of every finance plan

Boating Safety Reminders Put Real Ownership Costs in View?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Recent safety messaging from Australia’s boating sector is a timely prompt for buyers as warmer weather brings more traffic to ramps, rivers, bays and coastal waterways.
The message is practical rather than dramatic: check the vessel, carry the right equipment, understand local rules and plan for changing weather before heading out.

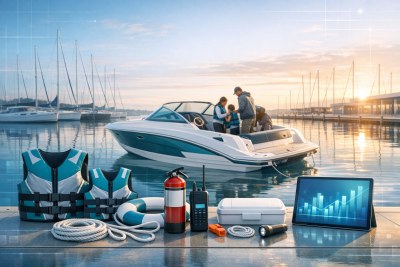
For anyone arranging boat finance, that safety focus has a direct budgeting lesson. The purchase price is only the starting point. A compliant and ready-to-use boat may also require life jackets, distress signals, navigation lights, fire safety equipment, radios, anchors, first-aid supplies, registration, licensing and insurance. On a used boat, buyers may also need to allow for servicing, battery replacement, trailer work, tyre upgrades or safety gear that is out of date.

This is where finance planning can become more realistic. A loan sized only around the advertised sale price may leave little room for the items that make ownership legal, safe and comfortable. Buyers should consider whether some upfront costs will be paid from savings, included in the broader purchase budget or staged over time. That decision can affect repayments, cash flow and the level of financial buffer available after settlement.

The safety push is also an extension of the earlier personal watercraft safety discussion, particularly where jet skis and high-performance craft share busy waterways with families, anglers, paddlers and larger vessels. For these buyers, the finance question is not just whether the craft is affordable, but whether training, storage, protective gear and insurance have been properly allowed for.

Used boat buyers should be especially careful. A well-priced vessel can still become expensive if a pre-purchase inspection identifies deferred maintenance or missing compliance equipment. Lenders may assess the age, condition and value of the boat differently, so buyers should avoid assuming every vessel will attract the same finance structure or interest rate.

Before committing, it is sensible to compare loan terms, fees and repayment flexibility alongside the vessel’s total setup cost. Factoring in ongoing ownership costs can help prevent a dream purchase from becoming a cash-flow strain once the first season begins.

The key takeaway is simple: safety preparation is not separate from finance preparation. A boat that is affordable on paper should also be affordable to equip, maintain, insure and operate responsibly. Buyers who build those costs into the plan from the start are better placed to enjoy the water with confidence.

Published:Thursday, 17th Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Finance News

What a Steady Rate Setting Means for Boat Buyers
17 Sep 2026: Paige Estritori
The Reserve Bank’s latest decision to keep the cash rate steady gives Australian boat buyers a useful moment to pause, but it should not be mistaken for a guarantee that borrowing costs will stay simple or uniform. For households looking at a first trailer boat, a fishing upgrade, a personal watercraft or a larger family cruiser, the lending market remains highly dependent on borrower profile, boat type, deposit size, loan structure and lender appetite. - read more
Why hardship support is now a bigger loan issue
17 Sep 2026: Paige Estritori
Financial hardship support is back in the spotlight across Australia’s lending market, with regulators and consumer advocates paying closer attention to how banks and non-bank lenders respond when borrowers ask for help. For households and small business owners already dealing with higher living costs, tax obligations, insurance premiums and uneven cash flow, this is more than a compliance story. It is a practical reminder that loan stress should be addressed before it becomes a missed-payment pattern. - read more
Card Spending Trends Keep Personal Loan Planning in Focus
17 Sep 2026: Paige Estritori
The Reserve Bank of Australia’s latest retail payments update offers another useful snapshot of how households are managing everyday spending, card use and short-term credit. While payment data is not the same as loan approval data, it can still tell borrowers something important: the way money moves through a household each month can affect how comfortable a lender feels about future repayments. - read more
Why Online Caravan Listings Need More Care Before You Pay
17 Sep 2026: Paige Estritori
Fresh consumer warnings about online vehicle scams are a timely reminder for caravan buyers to slow down before transferring deposits, sharing identity documents or arranging settlement. Caravans, camper trailers and motorhomes are high-value assets, and that makes them attractive targets for fake listings, cloned advertisements and sellers who pressure buyers to act quickly. - read more


Car Loans Articles

Car Loan Interest, Fees and Repayment Costs Explained
The total cost of a car loan is shaped by more than the advertised interest rate. Learn how rates, fees, loan terms, deposits, balloon payments and repayment frequency can affect what you pay over time. - read more
How Credit Scores Affect Your Car Loan Options
In the world of personal finance, a credit score plays a pivotal role in determining your borrowing power. But what exactly is a credit score? Simply put, it's a numerical representation of your creditworthiness, based on an analysis of your credit files. This score helps lenders assess the risk of lending you money or extending credit. - read more
Business Car Loans and Vehicle Finance Tax Considerations in Australia
Business vehicle finance can affect cash flow, GST, deductions, depreciation, private use records and fringe benefits tax. This guide explains the general tax concepts Australian small business owners and sole traders should understand before choosing a business car loan or vehicle finance structure. - read more
Smart Saving Strategies for First-Time Car Buyers
Welcome to a beginner's guide to saving for your first car! Buying a car for the first time is an exciting journey, filled with anticipation and, sometimes, a bit of anxiety. Rest assured, you are not alone on this path. Many Australians have taken these steps before you, and with the right strategies, you can turn this experience into a rewarding achievement. - read more


Free Assessment

Loan Amount:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Payday Loan:
A short-term, high-interest loan, typically due on the borrower's next payday.