Car Loan Finance Online :: News
SHARE

Share this news item!

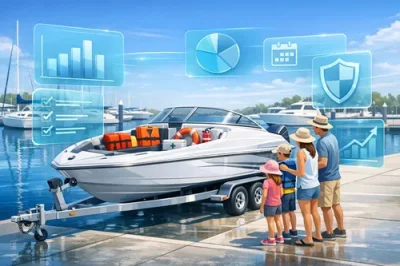
Spring Boating Push Puts Safety and Finance Planning Together

Warmer weather may lift inspections, but total ownership costs still need careful checking

Spring Boating Push Puts Safety and Finance Planning Together?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Spring is shifting Australia’s boating market into a more active phase, with warmer weekends likely to bring more inspections, test runs and conversations with dealers and private sellers.
Alongside that renewed interest, seasonal safety reminders are also becoming more important for anyone preparing to buy, upgrade or return a vessel to regular use.

For prospective owners, the practical message is that a boat budget should not stop at the advertised purchase price. Safety equipment, registration, insurance, servicing, trailer checks, storage, fuel and on-water accessories can all affect affordability. A boat that appears manageable on price alone may become more expensive once the full start-up and ownership costs are included.

This is especially relevant for first-time buyers and families moving from casual boating into ownership. Lifejackets, communication gear, navigation lights, flares where required, anchoring equipment and compliant capacity planning are not optional extras. They form part of responsible boating and, in many cases, must be organised before the first proper day on the water.

From a finance perspective, these seasonal reminders arrive at a useful time. Buyers considering a spring purchase should work backwards from a realistic monthly budget rather than forwards from a vessel they have already fallen in love with. That means allowing room for loan repayments, maintenance and the non-negotiable safety costs that support legal and confident boating. Before making an offer, it can help to estimate repayments across different loan amounts, interest rates and terms.

The same thinking applies to used boats, where a lower purchase price may be balanced by higher immediate spending. A pre-purchase inspection, engine service, battery replacement, trailer repairs or updated electronics can quickly change the numbers. Buyers should also check whether the vessel is free of encumbrances and whether the seller can provide clear documentation before finance settlement is arranged.

This update also extends the broader theme emerging through the spring buying season: more choice can create more urgency, but urgency should not replace due diligence. If a dealer promotion or private sale looks attractive, compare the complete cost of ownership and the proposed finance structure before committing. A sustainable boat loan is not just about getting approved; it is about making sure the boat remains enjoyable after the excitement of purchase day has passed.

For households planning to get on the water this season, the strongest position is to have finance expectations, safety requirements and ongoing costs mapped out before inspections begin. That preparation can make it easier to move quickly when the right boat appears, without overlooking the expenses that keep boating safe, compliant and financially comfortable.

Published:Thursday, 3rd Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Finance News

What a Steady Rate Setting Means for Boat Buyers
17 Sep 2026: Paige Estritori
The Reserve Bank’s latest decision to keep the cash rate steady gives Australian boat buyers a useful moment to pause, but it should not be mistaken for a guarantee that borrowing costs will stay simple or uniform. For households looking at a first trailer boat, a fishing upgrade, a personal watercraft or a larger family cruiser, the lending market remains highly dependent on borrower profile, boat type, deposit size, loan structure and lender appetite. - read more
Why hardship support is now a bigger loan issue
17 Sep 2026: Paige Estritori
Financial hardship support is back in the spotlight across Australia’s lending market, with regulators and consumer advocates paying closer attention to how banks and non-bank lenders respond when borrowers ask for help. For households and small business owners already dealing with higher living costs, tax obligations, insurance premiums and uneven cash flow, this is more than a compliance story. It is a practical reminder that loan stress should be addressed before it becomes a missed-payment pattern. - read more
Card Spending Trends Keep Personal Loan Planning in Focus
17 Sep 2026: Paige Estritori
The Reserve Bank of Australia’s latest retail payments update offers another useful snapshot of how households are managing everyday spending, card use and short-term credit. While payment data is not the same as loan approval data, it can still tell borrowers something important: the way money moves through a household each month can affect how comfortable a lender feels about future repayments. - read more
Why Online Caravan Listings Need More Care Before You Pay
17 Sep 2026: Paige Estritori
Fresh consumer warnings about online vehicle scams are a timely reminder for caravan buyers to slow down before transferring deposits, sharing identity documents or arranging settlement. Caravans, camper trailers and motorhomes are high-value assets, and that makes them attractive targets for fake listings, cloned advertisements and sellers who pressure buyers to act quickly. - read more


Car Loans Articles

Smart Saving Strategies for First-Time Car Buyers
Welcome to a beginner's guide to saving for your first car! Buying a car for the first time is an exciting journey, filled with anticipation and, sometimes, a bit of anxiety. Rest assured, you are not alone on this path. Many Australians have taken these steps before you, and with the right strategies, you can turn this experience into a rewarding achievement. - read more
Unlocking Savings: The Benefits of Refinancing Your Car Loan
Refinancing your car loan can be a game changer for your financial health. But what exactly does it mean? In simple terms, refinancing involves replacing your current car loan with a new one, usually to secure better interest rates or more favorable terms. - read more
How Personal Car Loans Work in Australia
Personal car loans can help Australians finance a new or used vehicle, but the right structure depends on the borrower, the car, the lender and the total cost of borrowing. This guide explains secured and unsecured car loans, repayments, deposits, loan terms, fees, eligibility and key questions to ask before applying. - read more
How the Car Loan Application Process Works in Australia
Applying for a car loan in Australia usually involves checking affordability, preparing documents, submitting an application, lender assessment, conditional approval, vehicle checks, contract signing and settlement. This guide explains the typical steps and what can affect the outcome. - read more

Car Loan Repayment Calculator

Car Loan Repayment Calculator

The Great Australian Side-Hustle

The Great Australian Side-Hustle

Stay informed with MoneyTips

Get practical financial information, news, guides and resources.


Knowledgebase
Mortgagor:
A person who offers to assign an asset as security (e.g. real estate) under a mortgage loan contract. The lender (mortgagee) holds the legal ownership of the security until the loan is repaid and the mortgage is discharged.