Car Loan Finance Online Business Loan Repayment Calculator
Estimate repayments with our Business Loan Calculator. Compare finance options, tailor loan terms, and plan with confidence for your business growth.
Calculator results are estimates only and not quotes. Actual quotes will be provided by licensed brokers after you submit an enquiry.
Business Loan Details:
Important!
Business Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.). To find out if you qualify ... and for a free, personalised interest rate and repayment quote,
please CLICK HERE
Business Loan Amortisation Calculator
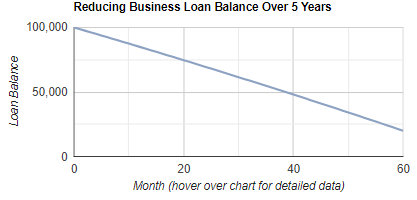
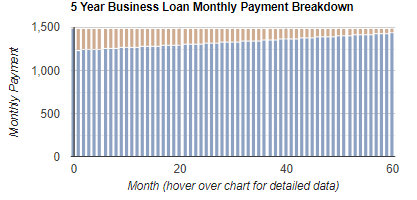
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Business Loan Repayment Calculator
Our Business Loan Repayment Calculator helps you estimate business loan repayments, compare finance options and understand the true cost of borrowing before you commit. It is important because small changes to your loan amount, interest rate, term or balloon payment can materially change cash flow, total interest and end-of-term obligations. This calculator provides an indicative estimate only and is designed to support planning and budgeting for business growth.
How to complete each section for the best result:
1. Loan Amount
Enter the amount you expect to borrow as a whole number (no dots or commas). Include any costs you plan to capitalise into the loan, such as stamp duty, registration, insurance or other applicable fees, so the estimate reflects your real financed amount.
2. Balloon or Residual Payment (optional)
Select a residual as a percentage of the purchase price. A higher residual usually reduces ongoing repayments, but increases the amount due at the end and can increase total interest over the term. Choose a residual only if you have a realistic plan to refinance, pay it out, or sell an asset to meet the final amount.
3. Term of Loan
Select the number of years you want to repay the loan. A longer term generally lowers periodic repayments but increases total interest paid. A shorter term can reduce total cost but may place pressure on cash flow.
4. Interest Rate
Select an indicative annual interest rate to run a scenario. Your actual rate depends on lender assessment and your business circumstances, so consider testing multiple rates to stress-test affordability.
How to interpret the results:
1. Repayment estimate
Use the repayment figure as a budgeting guide for regular cash flow planning. If you selected a residual, remember the final payout is additional to the periodic repayments.
2. Amortisation charts
Review the reducing loan balance over time and the split between interest and principal. Early repayments typically include a higher interest component, with principal reduction accelerating later.
General information only, not personal financial advice. It does not consider your objectives, financial situation or needs. Consider the loan contract, fees, repayment frequency, and whether the repayments remain affordable under higher rates or lower revenue, and seek professional advice if required.
Applying for a car loan in Australia usually involves checking affordability, preparing documents, submitting an application, lender assessment, conditional approval, vehicle checks, contract signing and settlement. This guide explains the typical steps and what can affect the outcome. - read more
Welcome to a beginner's guide to saving for your first car! Buying a car for the first time is an exciting journey, filled with anticipation and, sometimes, a bit of anxiety. Rest assured, you are not alone on this path. Many Australians have taken these steps before you, and with the right strategies, you can turn this experience into a rewarding achievement. - read more
Business vehicle finance can affect cash flow, GST, deductions, depreciation, private use records and fringe benefits tax. This guide explains the general tax concepts Australian small business owners and sole traders should understand before choosing a business car loan or vehicle finance structure. - read more
Personal car loans can help Australians finance a new or used vehicle, but the right structure depends on the borrower, the car, the lender and the total cost of borrowing. This guide explains secured and unsecured car loans, repayments, deposits, loan terms, fees, eligibility and key questions to ask before applying. - read more
Fresh September lending signals are giving Australian boat buyers another reason to slow down before signing a purchase contract. As the spring boating season gathers pace, lenders are still competing for well-qualified borrowers, but the gap between the cheapest-looking offer and the most suitable finance structure can be wider than many buyers expect. - read more
Fresh attention on Australian mortgage arrears is a reminder that repayment pressure is no longer just a theoretical risk for highly leveraged households. After a long period of elevated interest rates, higher insurance costs, bigger grocery bills and tighter household budgets, more borrowers are finding that even small financial setbacks can make loan commitments harder to manage. - read more
The Reserve Bank of Australia’s latest lending rate statistics are a useful reminder that personal borrowing costs can vary widely, even when the broader cash rate outlook appears steady. For households considering a car loan, debt consolidation loan or unsecured personal loan, the key issue is not simply whether rates are rising or falling. It is whether the loan being offered is affordable, suitable and competitive for the borrower’s circumstances. - read more
Recent caravan and RV safety coverage ahead of the spring touring season has put towing compliance back in the spotlight. For buyers, the message is broader than road safety alone. Aggregate trailer mass, gross trailer mass, towball download and payload can all affect whether a caravan is genuinely suitable for a household, a tow vehicle and a budget. - read more